Friday, July 19, 2013

Week #29 - Cheap Glasses & Free Lunch!

wow... here we are at week #29 if my silly little blog. I have to admit that I have some times when I just want to stop doing it because I see that only a few people have viewed it, but the feedback I get from a few of you (and my general OCD nature) are what keep me going! So a huge thank you to the OCD Savings Blog weekly readers and supporters. If you haven't joined please check out the Facebook group and contribute your tips, hints and even sales you find on the go! Here is the link... www.facebook.com/groups/ocdsavings


 There has not been a lot going on in the world of money this past week. I did get the free lunch bag that I ordered from Coca-Cola using my Coke points and I started using that to bring my lunch to work. I also went back to the Coke website and ordered a different bag that was also completely free using just my points. I'm a fan of Coca-Cola so I like some of the stuff they offer anyway, but when its something I can actually use or need and its free its pretty awesome!


August 15th is the 2 year anniversary since I got my last pair of free safety glasses at work which means I am eligible to get another pair. I went and got the forms from the HR department today and will be booking an eye exam soon. Two years ago when I went for an exam I gave them my Blue Cross card knowing that my insurance didn't cover any eye exams. I figured I would eventually get a bill to pay from the doctor, but two years later I still didn't get a bill so I think I'll have to find a different doctor to go to or risk them pulling my records and having to pay the bill! No matter where I go I'll get the form filled out and get a free pair of glasses through work, then I'll take all the measurements and prescription info and go to ZenniOptical.com and pick up a new pair of super cheap prescription sunglasses and maybe an extra pair of regular glasses for an emergency. If you haven't used Zenni, I highly recommend them. I got prescription sunglasses for $20 and they work perfect!


So this is the third week of the month which usually means my whole check will be going into my mortgage account, but I'm going to change it up this month! I got a little bit of overtime which made this check a big higher than usual so I will be putting this check towards my savings. The check I got is for $648.63 ($41.47 to my 401K) and I'm going to space it out in a few different spots. I'm going to take $148.63 off the top and put it in my regular checking account as part of my 'enjoy life' initiative. The remaining $500 will be broken down like this: $325.00 to the money market savings, $150 to the future car savings and $25 to the future vet bill account.


In addition to my paycheck I also cashed in some deposit cans & bottles, some of which were donated to me by a reader. I have to admit that I had mixed emotions about taking them because part of me felt like she should have cashed them herself and saved the money, but it was a little more free cash for me! So I ended up with $8.60 in can money to put in the piggy bank and I also did my weekly $20 vacation transfer. On to the wrap up....


Here is the week 29 wrap up:
$41.47 to my 401K
$325.00 to the money market savings
$150.00 to the future car savings
$25.00 to the future vet bill account
$20.00 to my vacation fund

$8.60 to the piggy bank

Which makes the 2013 totals:
$987.84 in my 401K
$580.00 in the vacation fund
$65.30 in the piggy bank
$400.00 in the quarterly loan payment account
$125.00 in my vet bill savings
$1583.00 in my money market
$1032.99 in my car account


 Bonus Round.... I always speak very highly of the bank I got to, but that doesn't mean they are perfect and never make mistakes. Last Friday I deposited most of my check in my mortgage account, but I put $50 in my loan repayment account. Well the teller made an error and when I checked my online banking it showed a $50 deposit and a $50 withdraw on the same day. Knowing I didn't take any money out and no cash back I called the 800# for the bank and they are in the process of fixing the error as I type this. The moral is... make sure you check your bank balances!!


Friday, July 12, 2013

Week #28 - Small Checks & Big Bills

So last week I was in a crappy mood and ended up posting the blog late because I took an extra day off to make a four day weekend over 4th of July. I don't have much of a story to tell this week, but I'll give you an update on some stuff that has gone on in the world of spending & saving..


1- I've been collecting 'Coke Points' off of the bottle caps & soda boxes for a couple of years now and I have over 5000 points saved on-line. I check the catalog of gifts you can get every once in a while to see if there is anything new and I have used points a few times to get a t-shirt, a coke bottle shaped cake pan & a few other things. Recently I needed a new lunch bag for bringing food to work and instead of buying one with real money, I found one on the Coca-Cola website and ordered it for 300 Coke Points which pretty much means I got it free!


2- I talked about making complaints when service or products are not what they should be and I recently got 2 $10 gift certificates from the corporate office of a local convenience store chain because of some band products I bought from one of their stores. When I brought them to the store and asked if I could use it to buy just 1 bottle of soda they said yes, but when I did they gave me back the remainder in cash.... once again... Free Money!


3- I didn't tell this story, but I went to Applebees with my wife and mother-in-law for dinner a couple of weeks ago and they screwed up 2 out of 3 meals. We let the waitress know and the manager came over and said they were remaking the food, but when we got the bill they had not taken even 1 item off the bill. We didn't say anything, but when I got home I sent an email and filled out a survey which got me a call from a district manager. I explained what happened and he apologized and then a few days later I got a $20 gift certificate in the mail!


4- I have a pretty standard Saturday routine that starts with a trip to Rubber Chicken Comics (Main St. Bellingham, MA) followed by lunch at the Subway next door. I have a points card for Subway and have accumulated over 200 points, which is enough for 3-4 free sandwiches, but can be used for free smaller items also. They just started a promotion called '$4 Lunch' which is a 6" sandwich and fountain soda for... you guessed it, $4. I have been getting the $4 lunch and using 15 of my 'Subway Points' to get a free bag of chips which means I'm eating a filling lunch for under $5!


5- I was on a shopping trip with my wife at an Old Navy store and while she was shopping I checked out the t-shirts. I found a pretty cool Delorean shirt that was actually just a Delorean graphic and not a Back to the Future image. Old Navy was having a 30% off everything sale, but I also managed to find the only shirt on the rack that had a discount price tag of $4.95 on it (regular price was $15.95 I think). When it was rung up it came up at full price, but when we pointed out to the clerk that there was a discount tag on it, he changed it to $4.95 and also gave us the 30% off making the shirt about $3.50. Even with the amount of shirts I already have I couldn't turn down that bargain!

Ok... so hopefully you can take a couple of those things and turn them into a bargain or savings of your own. Now on to the weekly wrap up... I got a paycheck for only $495.73 ($31.30 was added to my 401K) because I took July 5th off to make a 4 day weekend after the July 4th holiday. I was going to deposit the full check into the mortgage account because its a smaller check, but I'm still going to put $50 in the loan repayment account and the remaining $445.73 towards the mortgage. I also did my $20 vacation transfer again even though after paying my credit card bill the checking account is looking a little thin!

Here is the week 28 wrap up:
$31.30 to my 401K
$20.00 to my vacation fund

$50.00 to the loan repayment account

Which makes the 2013 totals:
$946.37 in my 401K
$560.00 in the vacation fund
$56.70 in the piggy bank
$400.00 in the quarterly loan payment account
$100.00 in my vet bill savings
$1258.00 in my money market
$882.99 in my car account


For this weeks bonus I'll just let you know that I got my car tax bill in last week. As much as it sucks to pay car taxes it was nice to know that I had money set aside to use for car expenses in my 'car savings account'. I just wrote a check, mailed it out and transferred the same amount from the car account to the regular checking account and I'm still left with money for repairs or a potential car down payment in the future. So start saving for those things now and you wont have to panic when the bills come in down the road!


Monday, July 8, 2013

Week #27 - no readers, no story...

I got a paycheck for $613.82 ($39.12 to my 401K). I deposited the whole thing into my checking account to pay bills and did my $20 vacation transfer.

Here is the week 27 wrap up:
$39.12 to my 401K
$20.00 to my vacation fund


Which makes the 2013 totals:
$915.07 in my 401K
$540.00 in the vacation fund
$56.70 in the piggy bank
$350.00 in the quarterly loan payment account
$100.00 in my vet bill savings
$1258.00 in my money market
$882.99 in my car account


Thats it.

Friday, June 28, 2013

Week #26 - It's The Half Year Wrap Up!

Welcome ladies and gentlemen to the half year wrap up of the one and only official OCD Savings Blog! I kind of get the feeling that none of the readers have been playing along at home to see how much they can save, but I've gotten some cool comments from people that read every week and its appreciated. I've mentioned it before, but I also started a Facebook page where you can post your tips for saving, suggestions or even post info about a sale you find on the go if you have a smartphone! You can check out the Facebook group here... www.facebook.com/groups/ocdsavings


Now since this is the half year wrap up I think I'm going to get right to this weeks income and see where it takes us. So this week I got a check for $578.10 and $36.68 went to my 401k. This is the fourth week of the month so this is the check that should be 100% saved. I mentioned last week that I was thinking about cutting back on some of the saving to try and 'enjoy life' a little bit more. So here is what I'm going to do. I'm going to put $400 into my money market saving so I can stay on track toward my goal for the year. I'm going to put $25 into my car savings account, it's not much, but I feel better putting in a small amount than putting none. I'm going to take the remaining $153.10 and put it in my checking account. I have a credit card bill to pay in the next few weeks and my checking account is currently negative (except for the hidden money which keeps it from ever actually being overdrawn). This month I've only used my credit card for gas and I used it to pay for the college class ($270) I start in a couple of weeks, but I spend so much on gas to get to work that the bill is still quite sizable.


This week I also had some cans to return (Facebook group members got a preview of that!) so I have $8.65 for the piggy bank and I did my weekly $20 vacation transfer.

Here is the week 26 wrap up:
$36.68 to my 401K
$20.00 to my vacation fund

$400.00 to the money market savings
$25.00 to the car savings account
$8.65 to the piggy bank

Which makes the 2013 totals:
$875.95 in my 401K
$520.00 in the vacation fund
$56.70 in the piggy bank
$350.00 in the quarterly loan payment account
$100.00 in my vet bill savings
$1258.00 in my money market
$882.99 in my car account


Now lets take a look at exactly what this all means....

The $875.95 in my 401k is nice, but it wont be touched until years from now so its kind of out of sight, out of mind. This could be more, but my company does not offer me a % match on my 401k contribution because I also have a (very small) pension I will get at retirement.

The $520 in the vacation fund is huge! That was all saved just by putting away $20 once a week and I know its not a ton of money, but even at this point it would be enough to put toward a modest vacation and if you had been doing this since this time last year you would have double that to spend on vacation.

The $56.70 in the piggy bank is really what I consider to be free money. If you live in Rhode Island and you drink soda then set aside 10 minutes a week and return the cans... its FREE MONEY! You can save it, spend it, buy lottery tickets, give it to your kids or a homeless person or donate it to any charity. Free money is good money!

The $350 in the loan payment account, does count, but since I have used some of it (to make a payment) its not really 'saved'. It is set aside for a specific purpose and I would suggest you do something like this for your car taxes or insurance payments. Then when the bill comes in your don't have to panic or stress about where to get the money.

The $100 in the potential vet bill account is kind of saved with the hopes of never needing it. I'm not crazy, I know that my cat will eventually get sick or die, but until then that money will sit and be added to. This way if something does happen to him I'll have the stress of dealing with a sick cat, but I won't have to worry as much about the bills associated with it.

The $1258 in the money market is what I am most proud of. The money in that is what I really consider to be my 'savings account'. Money goes in and hopefully never comes out, but it is thanks to money I had saved (before this blog) in that account that I was able to put a down payment on a house. I have a goal in mind for that account by the end of the year and as of now I am on track to meet it, but we will see!

Lastly the $882.99 in my car savings account is a nice cushion because everyone with a car knows that things break! Right now I actually need rear brakes and tires. Thanks to having some good friends I will get a good deal on the brake job and possibly a discount on the tires, but even if I don't I know that I have $883 that I can spend on fixing the car before I have to stress about how to pay it. That might not be enough to fix any problem, but its a good start!


So what that all breaks down to is I have saved $2760.99 in six months ($3110.99 if you count the loan payment money I set aside) and I got another $56.70 just by investing a few minutes a week to return deposit cans & bottles. I always wish it could be more, but I think that I did pretty well for the first half of the year especially when you factor in all the time out of work I had and the medical bills associated with my gallbladder surgery.

To put it one more way what I was able to do over the last six months was to save 21.13% of my net pay (23.80% if you include the loan repayment money). I'm the kind of person that doesn't feel like they are good at many things, but I'm proud (not braggy) about the money I've been able to save and I hope that you can be proud of your savings too.

I hope that you guys all keep reading for the rest of the year and that you start saving along with me. If you set aside $20 a week starting now you will have almost $500 for your Christmas shopping! Not a bad idea!

Friday, June 21, 2013

Week #25 - School & Kids & Money

Ok dedicated readers... I'm not going to lie to you... this week I am completely unprepared! I usually start writing this blog earlier in the week, fine tune it mid-week and then add the final dollar amounts before I post it on Fridays. Well, right now it is 8:27 am on Friday and I'm just writing for the first time this week. At least it was an eventful week in my life!


On Tuesday this week I left work early and went to speak with a councilor at CCRI (Community College of Rhode Island) and before I left I signed up for a 7 week certificate program to become a 'teachers assistant'. My goal is to work with developmentally challenged kids (or maybe adults) at some point. Its no secret that I hate my job and even though I know that if I leave I will make less money, I think it will be worth it and my wife is on board and supportive! So I put the $270 for the certificate program on my credit card (I'll get 1% cash back on that!) and I'll figure out how to pay it when the bill is due next month!


After I left CCRI I went to Woonsocket hospital where my sister-in-law had just delivered a baby (via C-Section) a few hours earlier. I have to be honest, I don't understand how people afford having kids. If both parents have to work, and most of the time they do, then daycare costs a fortune and just the first few years of diapers and formula are thousands of dollars! So here is a question for you, if you have kids, how do you afford it!? Even if a kid is not spoiled they still need stuff and its not like before you had a kid you had thousands of extra dollars laying around right!?

Her is a picture of me & Lily Winters. In this photo I'm 39 years old and shes about 7 hours old.


Well... seeing as I didn't really have a topic this week I think I'm gonna just get to the money talk. This week I got a paycheck for $593.62 (about $22 less than usual because I left a little early one day last week) and I had $37.65 added to my 401K. I'm going to take $50 and put it in my quarterly loan payment account and put the remaining $543.62 into the mortgage checking account. I also did my weekly $20 vacation transfer in preparation for Octobers vacation! I will let you in on a little secret, making that transfer put my checkbook 'in the red' and it currently shows a negative balance, but thanks to my 'hidden' money its only negative in my checkbook register and not in the actual balance! I'll get that all cleared up in the next week or so and just hope it doesn't go to far 'negative' before then!

Also, since this is week #25 it means that I have saved $500 just by making that weekly $20 transfer! Even if you only did $10 you would have $250, hell even $5 a week would be  $125! I implore you to set up a weekly transfer from your checking to a savings account... start small and build up, but don't let any more weeks slip by, start saving today!


Here is the week 25 wrap up:
$37.65 to my 401K
$20.00 to my vacation fund

$50.00 in the quarterly loan payment account

Which makes the 2013 totals:
$839.27 in my 401K
$500.00 in the vacation fund
$48.05 in the piggy bank
$350.00 in the quarterly loan payment account
$100.00 in my vet bill savings
$858.00 in my money market
$857.99 in my car account


For this weeks bonus I will just give you a quick preview of next week. It is the last check of the month which means it should be 100% saving, but I think I'm only going to save about 1/3-2/3's of it. I will have some deposit cans/bottles returned by then, but I think I'm in a slight re-evaluation mode of my 'excessive' saving and I might ease back a little. We'll see if I can stick to that or not next week.

Please check out the Facebook group here: www.facebook.com/groups/OCDSavings

Also send in your thoughts on how money changes and how you pay for things once you have kids. Were does that extra money come from? What do you go without? What changes?

Friday, June 14, 2013

Week #24 - What if the rainy day doesn't come?

So for the last 23 weeks I have been preaching to you that you should save as much money as you can at pretty much any cost. I've told you all the things you can cut out, all the things you can do to get 'free' money and all the things that you should be saving for. I've told you that even saving $5 a week will add up over the course of a year and I do believe all of those things, but I'm starting to wonder if there is a limit to how much someone should push themselves to save?


Last weekend my mother-in-law was talking about another family member and about how every time he got a paycheck he would 'pay himself first', meaning put a certain amount of money away for savings. Then as the week/month went on if he didn't have enough money to buy something he wanted, he would go without it. What I realized at that moment that I do the first half of that (paying myself first), but I don't always do the second half (going without) which is why by the end of most months I'm stressing about having the cash on hand to pay my credit card bill and its why those five week months are so huge in helping me catch up on things.


Now when I say I don't 'go without' I don't mean that I spend like crazy and even the couple of habits I have (comics & records) are well under control, but I do spend money. I go out to eat with my wife and we do stuff sometimes. Like today we are going to see the Pawtucket Red Sox because a good friend of ours' son is going to get to go on the field. Now the tickets to the game are only $12 which sounds really cheap but for both of us that will be $24. Plus the game is at 5:30 so we will eat dinner at the stadium and I'm trying to talk myself out of it, but I would like to get a new baseball hat also. That can quickly turn into a $75 night out!


So what I've been thinking is that maybe I should slow down a little and not stress as much about saving money. We've all heard the phrase 'saving for a rainy day' right? Well what if that rainy day never comes and you have this pile of money saved, but you missed out on a comic book, a new record or a baseball game that you really wanted to see? Was it worth it? Probably not. Now the check that I would 'save' is still two weeks away based on my budget, but what I'm thinking is that I might put 1/2 (or maybe 2/3's) into my money market savings and just take the rest to spend on something for my wife & myself to do. I mean I have a certain amount of money saved for when I need a new car or for car repairs, but I've been saving money towards it ever since my current car was paid off so don't I deserve to enjoy NOT having a car payment for awhile? I've already saved $857.99 towards a car just this year and some people don't have much more than that for a full down payment when they buy a new car! I haven't decided for sure yet if I'll stop the car saving or not, but I wanted to let you know that I was thinking about it at the very least.


Ok, so here are the details on this weeks income. I got a paycheck for $662.80. It was a little more than usual because at my work we have this insane thing called a 'vacation bonus'. It was put in the union contract in the 70's as 'beer money' for when a guy went on vacation. Its supposed to be $50 the first week of vacation you take and $15 for each additional week. It used to be paid out during the weeks the employee was on vacation, but the company screwed it up and forgot to pay it so many times that now everyone gets a lump sum in June. So for example I get 3 weeks of vacation so my 'vacation bonus' was for $80 in this weeks check. Yeah... Its crazy and no I'm not making it up! So of my $662.80 I had $42.32 go to my 401K pre-tax and I'm going to put $50.00 in the quarter loan payment account and the remaining $612.80 in my mortgage checking account. I also made my standard $20 vacation transfer this week.

Here is the week 24 wrap up:
$42.32 to my 401K
$20.00 to my vacation fund

$50.00 in the quarterly loan payment account

Which makes the 2013 totals:
$801.62 in my 401K
$480.00 in the vacation fund
$48.05 in the piggy bank
$300.00 in the quarterly loan payment account
$100.00 in my vet bill savings
$858.00 in my money market
$857.99 in my car account


for this weeks bonus I will remind you that a couple of weeks ago I was talking about buying a new hockey jersey because the one I had was much to big since I lost weight. Well, I got an offer from a reader of this blog to trade my XXXL Gerry Cheevers winter classic jersey for his XXL Brad Marchand 2011 Stanley Cup jersey. We made the trade today and we are both happy. I'm sad to see the Cheevers jersey go because it was a special one, but I rather someone wear it than have it sit in my closet unworn!


Friday, June 7, 2013

Week #23 - Loyalty vs Generics

I'm always looking for a deal, a discount or a savings of some kind. I'll drive a few minutes out of my way to make sure I'm getting the best deal I can on gas and I've been known to come pretty close to totally running out of gas before I finally fill up knowing I'm at the cheapest area station. The way I look at it, all the gas is pretty much the same and I'm not going to get worse gas at Cumberland Farms then I am at A.J.'s Mini Mart. There are a lot of things that I treat the same way, I'll buy the cheapest (used) clothes because I don't really care about brand names and even though it may be sacrilege to many people I don't care what brand of ketchup I have and I'm totally happy with a generic brand.


One of the few things that I have found is not always worth skimping on is Soda. It might be because I'm a big fan and a connoisseur of fine sodas, but to me there really is a big difference from brand to brand and its one of the few things where a generic can really be sub par! Today I stopped at a Tedeschi's convenience store to get a soda and was going to grab a 2 liter bottle of Diet Coke which was $1.94 when I noticed that a bottle of the store brand Diet Cola was only .99 cents. I decided to take a chance and I'll be honest, a few sips in I'm not sold! I MIGHT give it another shot, but the odds are better that I will revert back to my usual Diet Coke, or even better is Coke Zero.


So... with that being said, I urge you to not be afraid to try a generic or a discounted product, but even if your as cheap as I am (you're probably not) be willing to admit when the savings is not worth it for the difference in quality and your enjoyment of the item.

Alrighty now...  So here we are on the first Friday of a new month which means my entire paycheck of $615.36 ($39.12 taken out pretax for my 401K) will be going into my checking account to pay my monthly bills, credit card, gas, food etc. The only savings this month will be my $20 vacation savings transfer unfortunately, but $20 saved is better than nothing right!? So here is the weekly wrap up...


Here is the week 23 wrap up:
$39.12 to my 401K
$20.00 to my vacation fund


Which makes the 2013 totals:
$759.30 in my 401K
$460.00 in the vacation fund
$48.05 in the piggy bank
$250.00 in the quarterly loan payment account
$100.00 in my vet bill savings
$858.00 in my money market
$857.99 in my car account


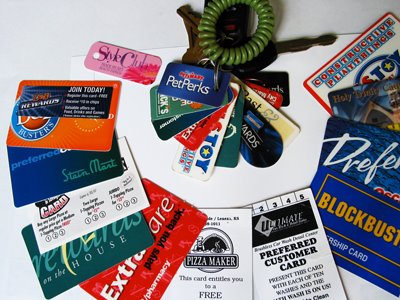
I remember when the only real 'Loyalty Card' that you needed to carry was for Stop & Shop, but now it seems that every single store out there has one and if you don't sign up you have to pay higher prices, you don't get any free coupons and you're generally looked down upon by clerks and customers. With all the different stores out there you need a huge wallet or a janitor size keychain to carry every loyalty card you could possibly need on a shopping trip.
There are few ways to avoid carrying all the cards, I know some stores will look up your 'loyalty card status' with your phone number and there are smart phone apps that will store all your 'loyalty card' info and allow the clerk to scan the screen of you phone. Now I'll let you know what I have done to remedy the situation. There are a couple of cards I use all the time that I carry the full size cards for (Subway, Stop & Shop) but for the stores I dont' visit that often what I did was I took the keychain size ones and cut them so it was almost just the barcode left. Then I took 3 of them and taped them together into the size of one full size card. I wrote on the tape the name of each store and covered it with more tape so it would not wear off. Then I repeated that whole process and taped those 3 to the back of the first three giving me six 'loyalty cards' that take up the space of one single card!
 
 
In the above photo you can also see that on my Subway card I taped the information about how many points you need for each reward. I did this because its not posted in every store and I knew that I would never remember! So now every time I look at the card I know what I can get for free!